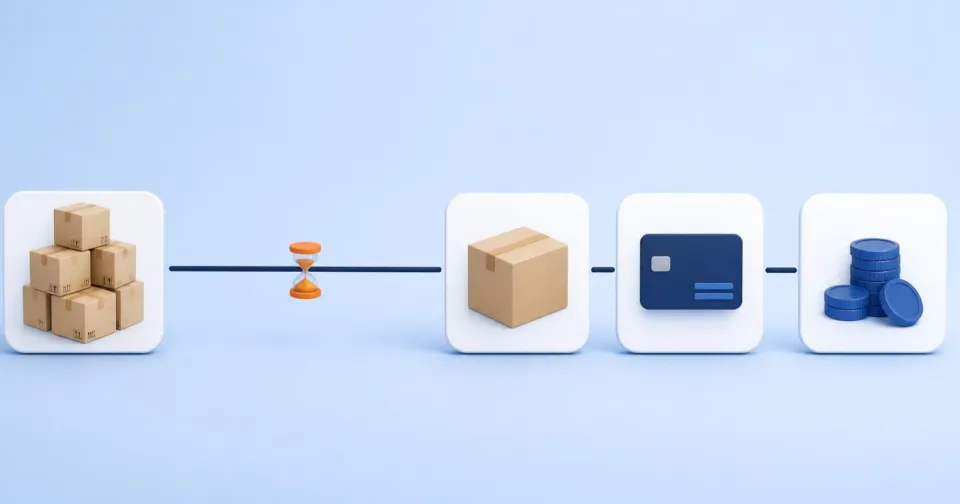
When an online store reports a profit yet the bank account is nearly empty, the accounts are usually not wrong. Profit and cash measure different things, and in a growing store they drift furthest apart. Money waits in stock, in transit from carriers and payment gateways, and part of it belongs to the tax office. The fix does not start with cost-cutting but with a map: how each koruna travels from buying goods to the customer’s payment, and where it stands still longest.
Why profit does not mean cash in the bank
Under accrual (double-entry) accounting, profit is calculated from the revenue and expenses that belong to a period, not from cash movements. Cash flows can therefore differ markedly from profit: revenue is recorded at one moment and the money arrives at another. Buying stock takes cash out of the account immediately, but reaches expenses only when the goods are sold. Conversely, a sale appears in profit even while the cash-on-delivery payment is still with the carrier. (Businesses using simple cash-based tax records see the shift differently, because stock purchases there usually count when they are paid.)
The gap between profit and cash is therefore not a loss. It is money standing somewhere in the business. The question is exactly where, and for how long.
The koruna’s journey: from purchase to payment
Corporate finance has a simple tool for this, the cash conversion cycle, described by Richards and Laughlin in 1980. It has three parts:
- Days inventory outstanding – how many days goods sit in stock on average before they sell.
- Days to collect – how many days after the sale it takes for the money to actually reach your account.
- Days payable outstanding – how many days after receiving goods you pay the supplier.
Cycle = days in stock + days to collect − days payable. A shorter cycle means less cash tied up in operations. It can even be negative: when customers pay upfront and suppliers give you payment terms, the customer’s money arrives before you have to pass it on.
In an online store, payment methods set the days to collect
For an online store this is not about invoices with payment terms but about how long money travels from the customer. Official documentation gives these timings:
| Payment method | When the money reaches the store’s account |
|---|---|
| Card via Shoptet Pay, daily payout | no later than the third day after the transaction (D+3) |
| Card or transfer via Comgate, daily payout | one to two working days after payment, depending on method and time |
| Weekly or monthly gateway payout | in one sum for the previous week or month |
| Cash on delivery via Zásilkovna (Packeta) | the second working day after delivery, i.e. only after shipping and pick-up |
| Bank transfer in advance | before the goods are dispatched |
The first practical conclusion: payout frequency is a setting, not fate. A monthly gateway payout on its own can lengthen collection by up to a month. Cash on delivery adds shipping days, weekends and the risk that the parcel is never collected.
Turn days into money
Days alone mislead, because each stage ties up a different amount. An illustrative example with invented numbers: a store sells CZK 30,000 a day excluding VAT and bought the goods for CZK 20,000.
| Stage | Days | Cash tied up |
|---|---|---|
| Goods in stock | 75 | CZK 1,500,000 (75 × 20,000) |
| Money in transit from gateways and carriers | 3 | CZK 90,000 (3 × 30,000) |
| Deferred supplier payments | −14 | −CZK 280,000 (14 × 20,000) |
| Total | 64 | CZK 1,310,000 |
This is a simplification using averages, but it is enough to set priorities. In this store more than CZK 1.3 million sits in stock at purchase prices, and the profit figure says nothing about it.
Why growth consumes cash
A profitable company that grows too fast can run out of cash even when its products succeed. How much growth a business can finance itself depends on the length of its operating cash cycle, how much cash each koruna of sales requires and how much cash each koruna of sales generates. Even a highly profitable business therefore needs additional working capital as it grows.
In the same example, if sales rise by 30% and the cycle stays at 64 days, cash tied up rises from CZK 1,310,000 to about CZK 1,703,000. The store has to find roughly CZK 393,000 upfront, mostly for larger stock. Meanwhile the growth adds about CZK 3,000 of gross margin a day (30% of CZK 10,000), before marketing and other costs. It takes more than four months for the extra margin to pay back the extra stock. Throughout, the profit and loss statement reports growth and the bank account reports emptiness.
That does not make growth a mistake. It means a growth plan needs, next to the revenue line, a line for “how much cash it will take and where it comes from”.
Your store data in one place
Korzaro connects store, marketing and operations data so you can make decisions from it.
Cash in the account that is not yours
The opposite mistake happens when there seems to be plenty of cash. A VAT-registered business collects VAT from customers and pays it over later. In the Czech Republic the VAT return is due within 25 days after the end of the tax period, and the tax is payable by the same deadline. The standard period is a month; under statutory conditions it can be a quarter. For advance payments the VAT obligation arises on the day the payment is received.
In practice, VAT on a whole month’s sales, or a whole quarter’s for quarterly filers, sits in the account for several more weeks. Anyone who counts it as free cash orders stock they cannot really afford, and the problem surfaces on the 25th.
Where to find the delay worth shortening
With the map in money, the order becomes clear. In the example, cutting stock from 75 to 60 days would free CZK 300,000, extending supplier terms from 14 to 30 days CZK 320,000, and speeding up collection from 3 days to 1 only CZK 60,000.
Stock. Usually the largest item, but not every extra day is a mistake. Longer stock can be justified by a better purchase price, a long lead time or goods that cannot be reordered. Look mainly for goods that sit for a long time without such a reason.
Suppliers. Payment terms are negotiable. Between businesses, Czech law sets a default of 30 days where nothing else is agreed, and terms longer than 60 days must be expressly agreed and must not be grossly unfair to the supplier. Negotiate terms as part of purchasing conditions, not just price.
Customer payments. Check your gateway payout frequency and the share of cash-on-delivery orders. This lever is usually smaller, but often the fastest and cheapest.
What store data cannot show
Store data shows the value of stock (if products have purchase prices filled in), order dates and payment methods. It does not show your bank balance, loans, unpaid supplier invoices, wages or taxes. So do not conclude from sales and orders that the business is running short of cash, or that it is fine. The map shows where money stands; whether there is enough of it only your accounts and your bank can tell.
What to do now
- Calculate the three periods for the last quarter. Average days in stock, days from dispatch to money received by payment method, and actual payment days with your main suppliers.
- Turn each period into money. Stock and suppliers at purchase prices, collection at revenue excluding VAT.
- Pick one delay. The one that ties up the most cash and that you can influence without hurting availability or purchase prices.
- Check your gateway payout frequency. Unless you plan otherwise, daily payout shortens collection at no extra cost.
- Before a growth plan, calculate its cash need. How much extra cash larger stock will tie up and where it will come from, including the VAT you will pay over.